Nigeria’s New Crypto Tax Has Traders Asking One Question
Why should you pay a transaction tax before you have made a profit?
Explainer · Virtual assets · Stablecoins · P2P
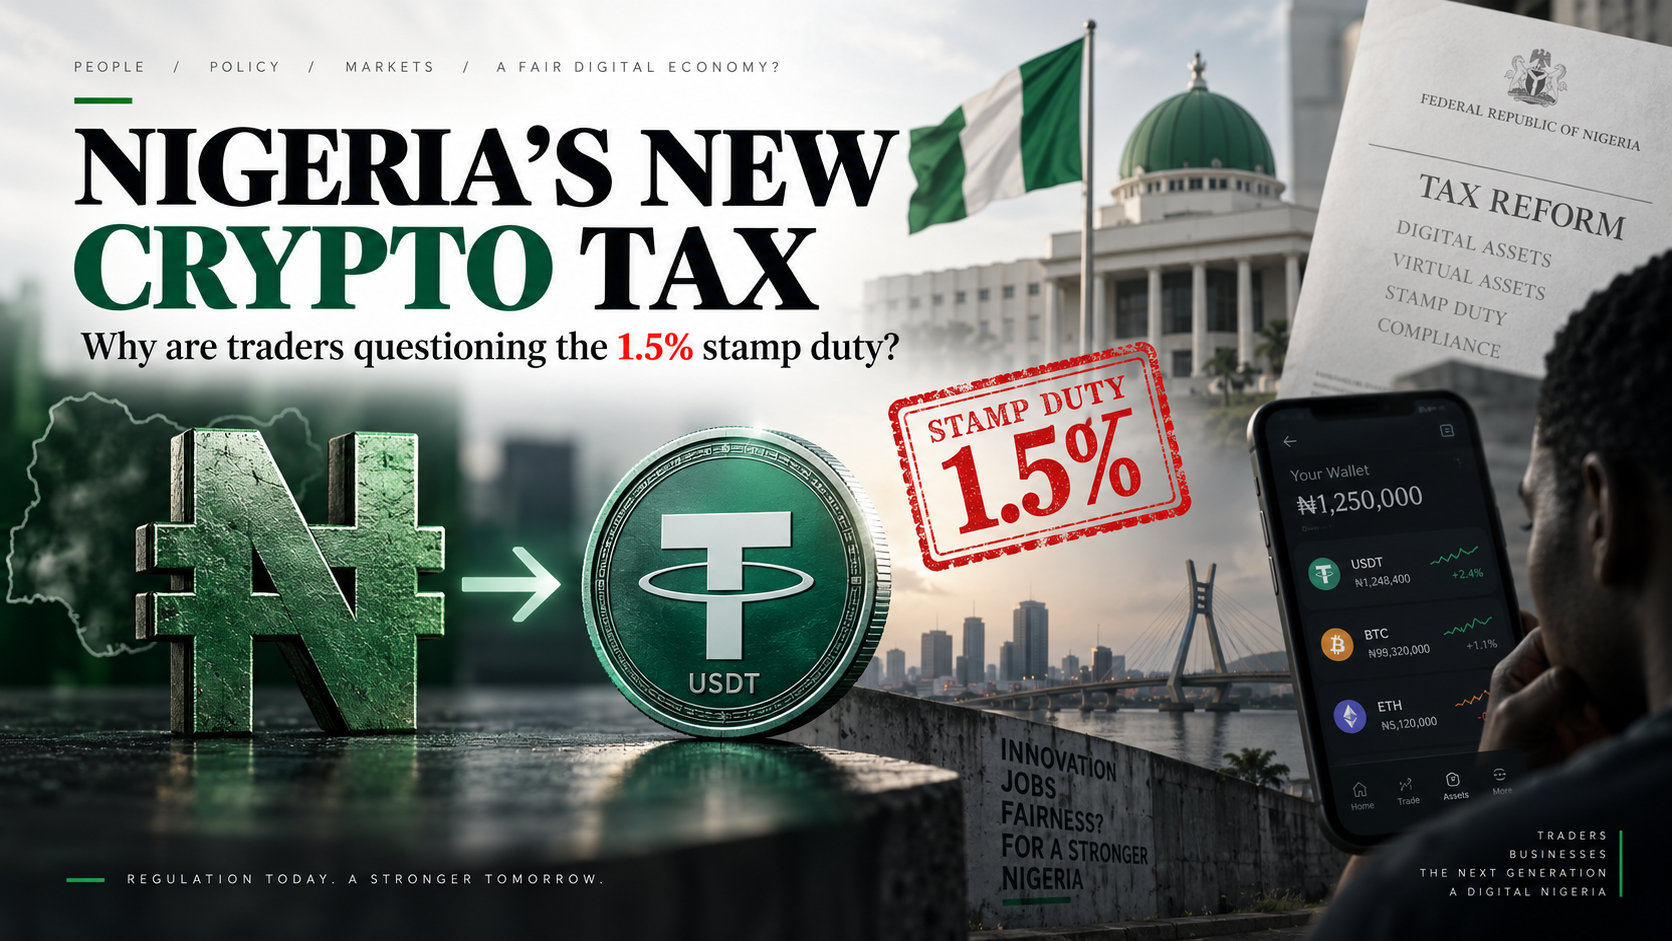
NIGERIA’S NEW CRYPTO TAX
The debate in one image: naira, stablecoins, regulation, and the 1.5% stamp-duty flashpoint.
THE ₦1,000,000 QUESTION
₦1,000,000
What happens before you even make a profit?
YOU PAY
₦1M
Naira → crypto
→
STAMP DUTY
1.5%
Potential eligible transaction cost
→
YOU RECEIVE
≈ ₦985K
Illustrative token value
Before profit:
you may already face a cost.
USDTDigital-dollar use case
P2PCould users move off-platform?
TaxNot one single charge
Illustrative example only. Actual treatment depends on the transaction, exemptions and implementation of the rules.
VIDEO EXPLAINER
Nigeria’s Crypto Tax Explained
1:28
A short explainer on Nigeria’s new virtual-asset tax rules and why the 1.5% stamp-duty debate matters.
Nigeria Revenue Service31 Jul 2026
A formal tax framework has arrived.
The NRS issued Information Circular No. 2026/21, explaining how Nigerian tax rules apply to virtual assets.
NRS Information Circular No. 2026/21 — official illustration of the 1.5% stamp-duty mechanism.
The argument
“Tax the profit, not the movement of money.”
That phrase captures the industry’s concern: a person may face transaction-related costs even when they have not yet made an investment gain.
It starts with ₦1,000,000.
Imagine you have ₦1,000,000. You are not chasing a 100x meme coin. You are not trying to gamble on the next token launch. You simply want to move part of your money into crypto — perhaps Bitcoin, perhaps a dollar-linked stablecoin.
Nigeria’s new virtual-asset tax guidelines make that ordinary act more complicated. The framework does not create one single “crypto tax.” Instead, it explains how several existing taxes can attach to different events.
The point attracting the loudest criticism is the 1.5% stamp duty mechanism for eligible fiat-to-token and token-to-fiat transfers. For users, the emotional reaction is easy to understand: if no profit has been made, why should a cost already appear?
This is not just one tax.
Income TaxApplies to taxable gains when a virtual asset is disposed of.
1% WHTA collection-at-source mechanism on certain gross disposal proceeds.
1.5% Stamp DutySet out for eligible fiat↔token transfers under the guideline framework.
7.5% VATGenerally relevant to taxable VASP service fees, not simply owning crypto.
These charges do not all apply to every transaction. Stablecoins also receive different treatment in some areas: legal analyses of the NRS guidelines note that disposals of Category 2 stablecoins such as USDT and USDC do not attract the 1% withholding tax that applies to some other asset categories.
Why USDT users care.
For many Nigerians, a stablecoin is not a speculative bet. It can function more like a digital dollar — a way to receive overseas freelance income, pay an international supplier, move money across borders or hold value outside the naira.
That is what makes this debate different from a normal “crypto traders versus the taxman” story. The people affected may include users who do not think of themselves as investors at all.
Illustrative example
₦1,000,000
− ₦15,000
≈ ₦985,000
Potential token value received under a simple 1.5% illustration
Not tax advice. The real result depends on the transaction, available exemptions and how the NRS rules are implemented in practice.
Why traders are angry.
The strongest objection is not necessarily to taxing investment profits. It is to adding friction to the movement between fiat money and virtual assets. Industry stakeholders have warned that extra costs on regulated platforms could make formal compliance less attractive.
That creates a policy problem. If the regulated route becomes noticeably more expensive while informal alternatives remain cheaper, some users may look for ways around the formal system.
Could this push users back toward P2P?
Nigeria has already lived through periods when restrictions pushed crypto activity toward peer-to-peer channels. That history is why the current debate matters. The government wants more visibility, reporting and compliance. But too much friction could create the opposite incentive.
The question is no longer whether crypto exists in Nigeria. It clearly does. The question is how to regulate and tax it without encouraging users to disappear into harder-to-monitor channels.
There are still open questions.
Professional tax analysis has also flagged issues that may need clarification, including the relationship between the NRS administrative guidelines and exemptions or thresholds contained in the underlying legislation.
That means the most dramatic version of the story — “every Nigerian crypto transaction is automatically hit with all of these taxes” — would be misleading. The real framework is more complicated, and implementation details matter.
Nigeria is no longer asking whether crypto should exist.
It already does.
The question now is how much friction can be added before users simply find another route.
⚠️
This site can only be viewed in Safari
Tap the “···” menu in the upper-right corner and choose “Open in Safari”.